Can I Cancel My Car Insurance If I Pay Monthly?
Yes, you can cancel your car insurance even if you pay monthly—but it’s not always straightforward. Depending on your insurer, contract terms, and timing, you may face fees, refund delays, or coverage gaps. Understanding your policy and following the right steps helps you avoid surprises.
Key Takeaways
- You can cancel anytime: Most insurers allow cancellation, but terms vary—check your policy or call customer service.
- Monthly payments don’t lock you in: Paying monthly doesn’t mean you’re stuck; you can still cancel, but may owe a fee or forfeit unused premiums.
- Watch for cancellation fees: Some companies charge $50–$100 or more, especially if you cancel mid-term without a valid reason.
- Get proof of new coverage first: Never drive uninsured—secure new insurance before canceling your current policy.
- Refunds may take time: Unused premiums are usually refunded, but processing can take 2–6 weeks depending on the insurer.
- State laws matter: Some states require insurers to notify you of cancellation rights or limit fees—know your local rules.
- Document everything: Keep records of cancellation requests, confirmation numbers, and refund details for your protection.
📑 Table of Contents
- Can I Cancel My Car Insurance If I Pay Monthly?
- Understanding Your Car Insurance Policy Terms
- Steps to Cancel Your Monthly Car Insurance Policy
- Potential Fees and Penalties When Canceling
- What Happens After You Cancel?
- Special Situations: When Cancellation Is Different
- Tips to Avoid Common Cancellation Mistakes
- Final Thoughts: Yes, You Can Cancel—But Do It Right
Can I Cancel My Car Insurance If I Pay Monthly?
So, you’ve been paying your car insurance monthly—maybe through automatic deductions from your bank account or credit card—and now you’re thinking, “Can I cancel my car insurance if I pay monthly?” The short answer is yes, you can. But the longer, more important answer involves understanding the fine print, potential fees, timing, and what happens next.
Car insurance is a legal requirement in almost every state, so canceling isn’t as simple as just stopping payments. If you let your policy lapse without replacing it, you could face fines, license suspension, or even trouble registering your vehicle. But if you’re switching insurers, selling your car, moving out of state, or simply no longer need coverage, canceling is not only possible—it’s often necessary.
The good news? Paying monthly doesn’t trap you in a long-term contract. Most insurers offer flexible payment plans precisely so customers aren’t locked into rigid agreements. However, that flexibility comes with conditions. Some companies treat monthly payments as part of a 6- or 12-month policy term, meaning canceling early could trigger penalties. Others allow month-to-month billing with minimal fees.
In this guide, we’ll walk you through everything you need to know about canceling your car insurance when you pay monthly—from understanding your policy terms to avoiding common pitfalls and ensuring a smooth transition to new coverage (or no coverage at all).
Understanding Your Car Insurance Policy Terms
Visual guide about Can I Cancel My Car Insurance If I Pay Monthly?
Image source: cdn.images.express.co.uk
Before you even think about canceling, you need to know what kind of policy you have. Not all car insurance plans are created equal, and the type of policy you hold directly affects your cancellation rights.
Most car insurance policies are issued for a specific term—typically six or twelve months. Even if you’re paying monthly, you’re likely still bound by that original term agreement. This means your insurer expects you to pay for the full duration unless you meet certain conditions.
Fixed-Term vs. Month-to-Month Policies
There are two main types of billing structures:
– **Fixed-term policies**: These are the most common. You sign up for a 6- or 12-month policy and agree to pay premiums over that period. Even if you pay monthly, you’re committed to the full term. Canceling early may result in a cancellation fee or forfeiture of unused premium.
– **Month-to-month policies**: Less common, but some insurers offer true month-to-month plans with no long-term commitment. These usually come with higher monthly rates but give you the freedom to cancel with little or no penalty—often with just 10–30 days’ notice.
To find out which type you have, check your policy documents or log into your insurer’s online portal. Look for language like “policy term,” “renewal date,” or “cancellation terms.” If it says your policy renews every six months, you likely have a fixed-term plan.
What Does “Pro-Rata” vs. “Short-Rate” Mean?
When you cancel mid-term, insurers use one of two methods to calculate your refund:
– **Pro-rata cancellation**: You get back the exact amount for the unused days. For example, if you paid $600 for six months and cancel after two months, you’d get $400 back—no extra fees.
– **Short-rate cancellation**: The insurer keeps a penalty fee on top of the earned premium. So, using the same example, instead of getting $400 back, you might only receive $350. This method discourages early cancellations and is common among insurers who want to protect their administrative costs.
Most major insurers use pro-rata refunds, but some smaller or specialty companies may apply short-rate calculations. Always ask which method applies before canceling.
Check for Early Termination Clauses
Some policies include clauses that allow you to cancel without penalty under specific circumstances—such as selling your car, moving to a state where the insurer doesn’t operate, or being called to active military duty. These are called “early termination rights” and can save you money.
For instance, if you sell your vehicle and provide proof (like a bill of sale), many insurers will waive cancellation fees. Similarly, if you’re relocating to another state and your current insurer doesn’t offer coverage there, they may let you cancel early with a full or partial refund.
Always read your policy’s “Cancellation” section carefully. It’s usually buried in the fine print, but it holds the key to understanding your rights.
Steps to Cancel Your Monthly Car Insurance Policy
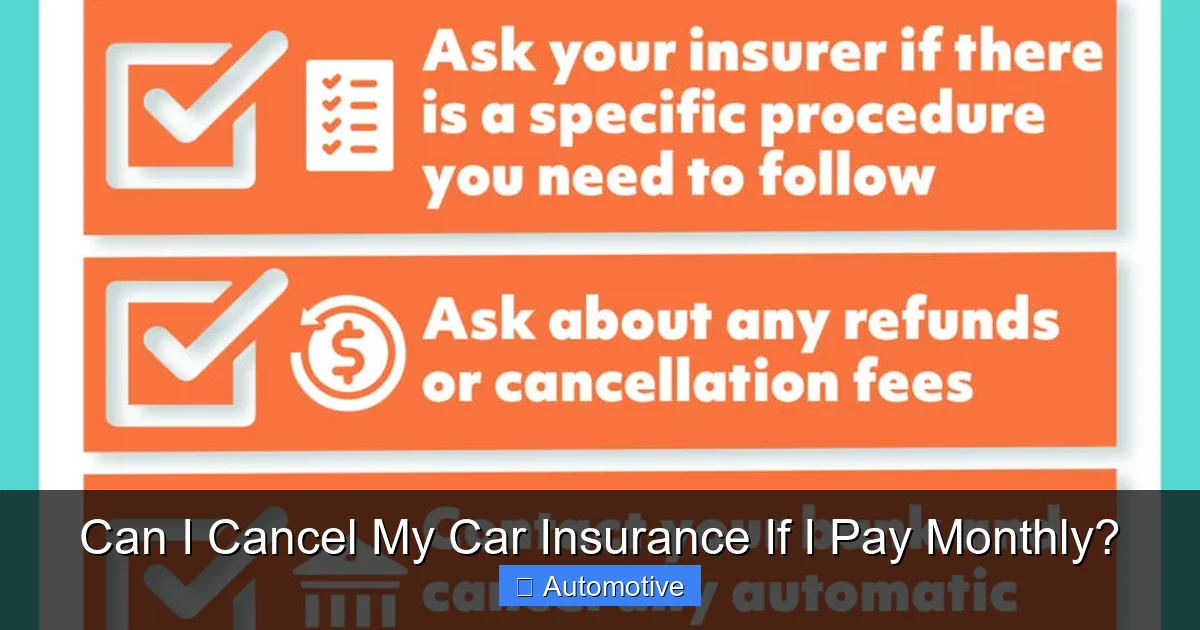
Visual guide about Can I Cancel My Car Insurance If I Pay Monthly?
Image source: mychoice.ca
Canceling your car insurance doesn’t have to be stressful—if you do it the right way. Follow these steps to ensure a smooth, penalty-free (or low-penalty) cancellation.
Step 1: Review Your Policy and Confirm Cancellation Terms
Start by pulling up your policy documents or logging into your insurer’s website. Look for:
– Policy term length
– Cancellation policy (pro-rata or short-rate)
– Any early termination fees
– Required notice period (usually 10–30 days)
If anything is unclear, call customer service and ask a representative to explain your cancellation options. Get their name and note the date and time of the call.
Step 2: Secure New Coverage (If Needed)
Never cancel your current policy before securing new insurance—unless you’re permanently removing the vehicle from the road (e.g., selling it or storing it long-term).
Driving without insurance is illegal in nearly every state and can result in:
– Fines ($100–$1,000+)
– License suspension
– Vehicle impoundment
– Higher future premiums due to a lapse in coverage
If you’re switching insurers, get a new policy effective on or before your current one ends. Most insurers let you set a future start date, so coordinate the timing carefully.
Pro tip: Use online comparison tools to find a better rate. Even a small monthly savings adds up over time.
Step 3: Notify Your Insurer in Writing
While some insurers allow cancellations over the phone or online, it’s safest to send a written cancellation request. This creates a paper trail in case of disputes.
Your cancellation letter should include:
– Your full name and policy number
– Vehicle details (make, model, VIN)
– Effective date of cancellation
– Reason for cancellation (optional but helpful)
– Signature and date
Send it via certified mail or email with a read receipt. Keep a copy for your records.
Example:
> “Dear [Insurer Name],
> I am writing to formally cancel my auto insurance policy #123456789, effective [date]. My vehicle, a 2020 Honda Civic (VIN: XXXXXXXXXXXXXXXX), will no longer be insured under this policy as I have secured coverage elsewhere. Please confirm cancellation and process any refund due on a pro-rata basis.
> Sincerely,
> [Your Name]”
Step 4: Confirm Cancellation and Refund
After submitting your request, wait for written confirmation from your insurer. This should arrive within 7–14 days and include:
– Confirmation of cancellation date
– Refund amount (if applicable)
– Method and timeline for refund (check, direct deposit, etc.)
If you don’t hear back within two weeks, follow up. Insurers are required by law in most states to respond to cancellation requests promptly.
Step 5: Cancel Automatic Payments
If you set up auto-pay through your bank or credit card, don’t forget to cancel it. Otherwise, you might be charged for a month you’re no longer insured—and getting that money back can be a hassle.
Log into your bank’s bill pay system or contact your credit card company to stop recurring payments. Do this only after confirming your policy is canceled.
Potential Fees and Penalties When Canceling
Visual guide about Can I Cancel My Car Insurance If I Pay Monthly?
Image source: blog.fincrew.my
Let’s be honest: canceling car insurance isn’t always free. Depending on your insurer and timing, you might face fees or lose part of your premium.
Common Cancellation Fees
– **Early termination fee**: $50–$150, charged if you cancel before the policy term ends.
– **Administrative fee**: $10–$30, covers processing costs.
– **Short-rate penalty**: As mentioned earlier, this reduces your refund beyond the unused premium.
For example, State Farm and GEICO typically use pro-rata refunds with no cancellation fee if you provide proof of new coverage. But smaller insurers like The General or Dairyland may charge $75–$100 regardless.
When Fees Are Waived
You can often avoid fees if:
– You’re replacing your policy with another insurer (provide proof)
– You’re selling the vehicle (submit a bill of sale)
– You’re moving out of state
– You’re deployed in the military
Always ask if fees can be waived—many customer service reps have discretion to do so.
State-Specific Rules
Some states regulate cancellation fees. For example:
– **California**: Insurers cannot charge a cancellation fee if you provide proof of new coverage.
– **New York**: Cancellation fees are capped at $50.
– **Texas**: Insurers must refund unused premiums within 30 days.
Check your state’s Department of Insurance website for specific rules.
What Happens After You Cancel?
Canceling your policy doesn’t end your responsibilities. Here’s what to expect next.
Refund Processing
If you’re due a refund, it typically takes 2–6 weeks to arrive. The method depends on how you paid:
– Credit card: Refund appears in 3–5 business days
– Bank account: 5–10 business days
– Check: Mailed within 2–4 weeks
If it’s been over six weeks, contact your insurer. Delays can happen, but they’re not an excuse to ignore your refund.
Proof of Prior Coverage
Some states require proof of continuous insurance when registering a vehicle or renewing your license. Keep your cancellation confirmation and prior policy documents for at least 3–5 years.
If you ever need to prove you were insured, these records will save you from being flagged for a lapse.
Impact on Future Insurance Rates
A clean cancellation (with no lapse in coverage) won’t hurt your rates. But if there’s a gap—even a few days—you could be classified as a “high-risk” driver, leading to higher premiums.
To avoid this, always overlap policies by a day or two. For example, if your old policy ends June 30, start the new one June 28.
Special Situations: When Cancellation Is Different
Not all cancellations are the same. Here are a few unique scenarios and how to handle them.
Selling Your Car
If you’re selling your vehicle, you can cancel your policy as soon as the sale is complete. Provide the insurer with:
– Bill of sale
– Title transfer document
– Odometer reading (if required)
Most insurers will cancel immediately and refund unused premiums on a pro-rata basis.
Storing or Parking Your Car Long-Term
If you’re not driving your car (e.g., during winter storage or while traveling), consider switching to “storage insurance” instead of canceling entirely. This covers fire, theft, and vandalism but not collision—and costs much less.
Canceling completely leaves your vehicle unprotected against non-driving risks.
Moving Out of State
If you’re relocating, your current insurer may not operate in your new state. In that case, you can cancel without penalty. Just provide your new address and proof of residency (like a lease or utility bill).
Some insurers will even help transfer your policy to a partner company in your new location.
Tips to Avoid Common Cancellation Mistakes
Mistakes happen—but they’re easy to avoid with a little planning.
Don’t Just Stop Paying
Stopping payments without formally canceling can lead to:
– Late fees
– Policy cancellation by the insurer (with negative marks on your record)
– Debt collection
Always cancel properly, even if you’re behind on payments.
Don’t Assume Online Cancellation Is Enough
Some insurers let you cancel online, but if the system glitches or your request isn’t processed, you could still be on the hook. Follow up with a phone call or email to confirm.
Don’t Forget About Add-Ons
If you added roadside assistance, rental reimbursement, or gap insurance, make sure those are canceled too. They may have separate terms and fees.
Keep Records for at Least 3 Years
Store digital copies of your cancellation letter, confirmation, and refund check. You never know when you’ll need them.
Final Thoughts: Yes, You Can Cancel—But Do It Right
So, can you cancel your car insurance if you pay monthly? Absolutely. But it’s not just about hitting “stop payment” and walking away. Your ability to cancel—and whether you’ll pay fees—depends on your policy type, timing, and how you handle the process.
The key is preparation. Read your policy, secure new coverage if needed, notify your insurer in writing, and keep records. By following these steps, you can cancel cleanly, avoid penalties, and stay compliant with the law.
Remember: car insurance is there to protect you—not trap you. With the right knowledge, you’re in control of your coverage, your payments, and your peace of mind.
Frequently Asked Questions
Can I cancel my car insurance immediately if I pay monthly?
Yes, you can request immediate cancellation, but your insurer may require a notice period (usually 10–30 days). Some allow same-day cancellation if you provide proof of new coverage.
Will I get a refund if I cancel mid-term?
Most insurers refund unused premiums on a pro-rata basis, meaning you get back the exact amount for the days you didn’t use. However, some may charge a short-rate fee, reducing your refund.
Do I need to cancel if I sell my car?
Yes, you should cancel your policy once the sale is complete. Provide the bill of sale to your insurer to avoid future charges and ensure a smooth refund process.
Can my insurer charge a fee for canceling?
Some insurers charge cancellation fees, especially if you cancel early without a valid reason. Fees typically range from $50 to $150, but may be waived with proof of new coverage.
What happens if I cancel but don’t get new insurance?
Driving without insurance is illegal in most states and can result in fines, license suspension, or higher future premiums. Only cancel if you’re no longer driving the vehicle.
How long does it take to get my refund after canceling?
Refunds usually take 2–6 weeks, depending on your payment method. Credit card refunds are fastest (3–5 days), while checks may take up to a month to arrive by mail.